Your deductible can change the real cost of a storm. Translate it into dollars.
A homeowners policy may use a flat-dollar deductible or a percentage-based deductible for certain losses. The percentage is commonly applied to a policy coverage amount—not to the size of the repair bill. Read the declarations page before assuming what you would owe.
Build My Deductible Check →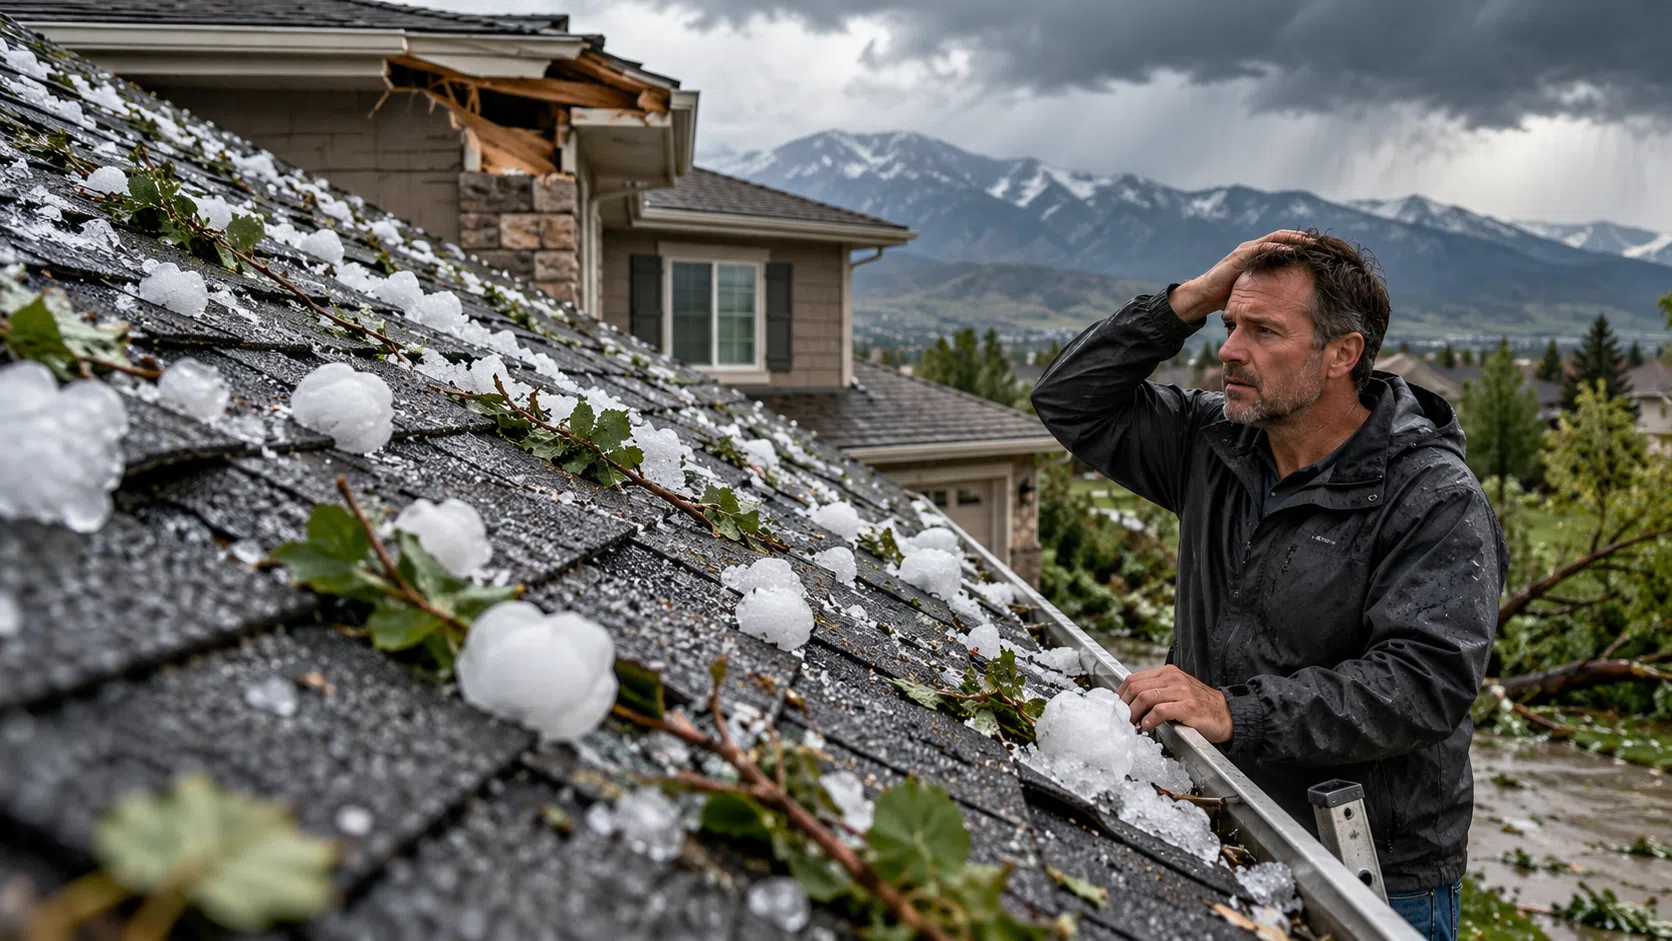
The premium is only half the affordability question.
A lower premium can come with more risk retained by the homeowner. HAVRYO makes the deductible visible in dollars so different policies can be compared on something more meaningful than monthly or annual price.
Flat or percentage?
Identify whether the applicable deductible is stated as a dollar amount or a percentage and whether a separate wind/hail deductible applies.
Percentage of what?
Do not multiply the percentage by repair cost. Identify the policy amount the deductible provision actually references.
Which loss triggers it?
A policy can contain different deductibles for different causes of loss. Match the number to the actual peril and policy wording.
Could you fund it?
Translate the deductible into dollars and decide whether that retained exposure is financially workable before choosing coverage.
Hail makes deductible design especially consequential.
Colorado's insurance market has experienced substantial hail-related losses. That makes wind/hail deductibles and roof settlement provisions important parts of policy comparison—not fine print to discover after damage.
HAVRYO does not decide whether a deductible applies to a particular claim. It helps the homeowner understand the policy terms before or after an insurance change and identify questions for a licensed insurance professional.
Start with the declarations page
Capture the listed deductibles, Coverage A or other referenced limits, and any separate wind/hail provision or endorsement.
Deductible is not the only roof variable
ACV versus replacement-cost treatment, roof age and applicable endorsements can materially change loss economics in addition to the deductible.
Same premium does not mean same retained risk
Two policies should be compared using both annual cost and the dollar exposure created by their deductibles and settlement terms.
No claim determination
The tool can explain and calculate policy inputs supplied by the homeowner; coverage and claim determinations remain policy- and insurer-specific.
Turn policy percentages into real-dollar exposure.
This is a natural HAVRYO calculator: enter the policy-specific coverage amount and deductible exactly as shown in the documents, then see the arithmetic without pretending to estimate a claim payout.
Check My Deductible →Flat dollar or percentage-based.
Use the amount referenced by the actual deductible provision.
Percentage or dollar amount from the policy.
Simple transparent arithmetic—no hidden insurance assumptions.
Review premium, deductible and relevant roof/coverage terms together.
Know what the percentage means before you need the policy.
Translate the deductible into dollars, identify which losses trigger it and compare the retained risk alongside the premium.
Build My Deductible Check →